Now this is a good one, because today’s news actually happened today. Let’s dig in.
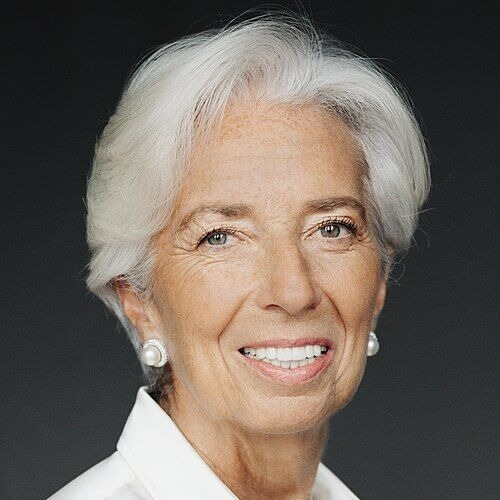
So the European Central Bank has done it. Today, Christine Lagarde flicked the switch on Pontes, the ECB’s new digital euro platform. Not for you. Not for me. Only for banks. This is the opening act of a much bigger show, the pilot phase ahead of a full digital euro trial planned for mid-2027, with actual issuance pencilled in for 2029 if everything goes to plan, which, let’s be honest, is a big if when you’re talking about Brussels bureaucracy.
Let’s be clear about what Pontes actually is, because the coverage has been predictably vague. This isn’t the retail digital euro you’ll eventually be tapping at the corner shop. That’s a separate project, the one with 36 payment providers, including Deutsche Bank, Revolut and UniCredit, lined up to test consumer-facing digital euro payments from the second half of 2027. Pontes is the wholesale layer underneath it all, a platform restricted entirely to credit institutions. Banks talking to banks, on the ECB’s terms, on the ECB’s rails.
So why should you care about a plumbing project only banks get to use?
Because plumbing is exactly where power gets built. Nobody notices the pipes until the water stops flowing, and by then it’s too late to complain.
Here’s what’s really going on. The ECB isn’t shy about its motives anymore. Isabel Schnabel practically said the quiet part out loud last month, warning that dollar-pegged stablecoins like Tether’s USDT and Circle’s USDC pose a genuine threat to European monetary sovereignty. Translation: America’s stablecoins are quietly colonising European payments, and Frankfurt is terrified of becoming a monetary vassal state to Silicon Valley and Wall Street. Pontes is the opening move in a defensive war for financial control, dressed up in the language of modernisation and innovation.
And look, I understand the instinct. Nobody wants their entire payments system running on rails controlled by a foreign country’s private companies. That’s a legitimate concern, and if you’ve been paying attention to how stablecoins have quietly become the dominant use case in crypto, you’ll know the ECB has a point.
But here’s where I part ways with the cheerleaders.
A central bank building the infrastructure for a state-controlled digital currency is not the same thing as protecting your financial freedom. It’s the opposite. Right now, this is bank-only, low drama, boring plumbing. But the direction of travel is unmistakable. Once Pontes is bedded in, once the retail pilot launches in 2027, once the legislation clears the European Parliament, you are looking at a central bank digital currency with the technical capability to track, programme and potentially restrict how you spend your own money. The ECB insists it will preserve privacy and freedom of choice. Forgive me if I don’t take a central bank’s word for it on privacy, especially one currently building surveillance-capable financial infrastructure under the banner of “sovereignty.”
Every authoritarian instinct in financial history has arrived wearing a friendly acronym and a promise that this time it’s different. Pontes might be the most polite, most Brussels-sounding bridge ever built. But bridges go both ways, and I’d want to know exactly who’s walking across it before I trust what’s on the other side.
Watch this space. The pilot starts quiet. It never stays that way.
That’s Cointiculate. Straight talk, no spin.